SK hynix Q3 2026 Earnings: 104.6T Won Revenue, 80% Margin
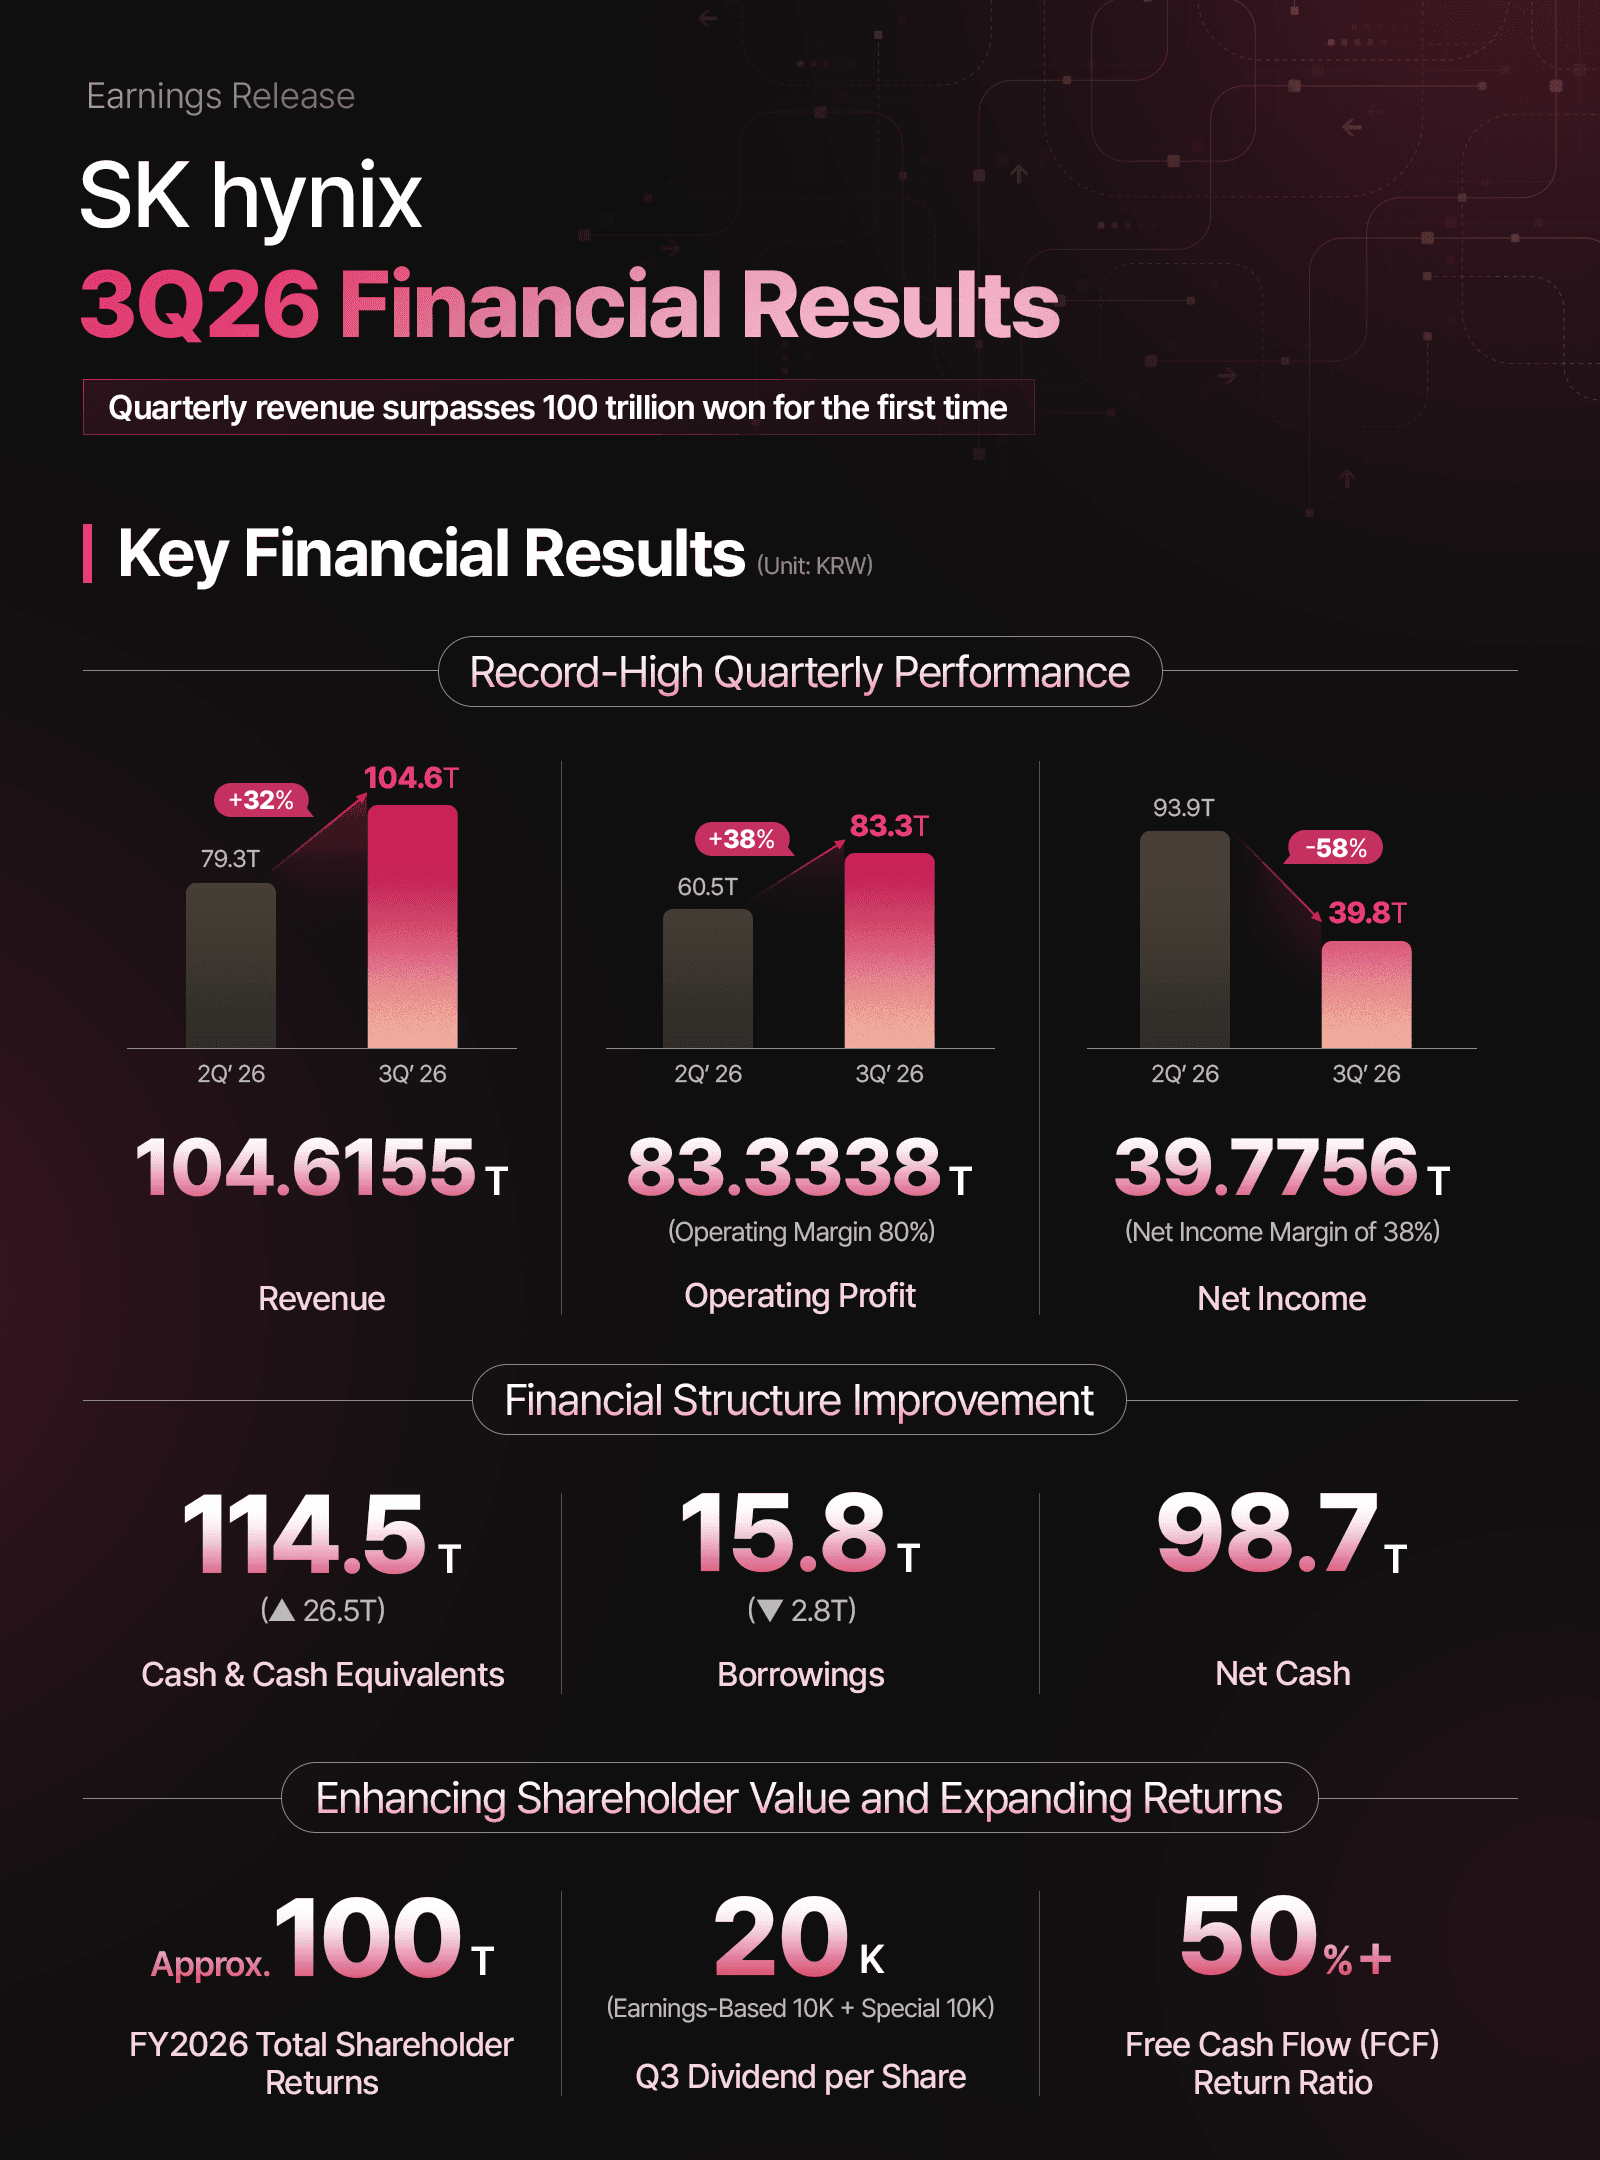
SK hynix reported record results for the third quarter of 2026 on October 28. Revenue was 104.6 trillion won, the first quarter above 100 trillion won in the company's history, and operating profit was 83.3 trillion won, an operating margin of 80% (SK hynix). High-bandwidth memory (HBM) for AI accelerators, server DRAM and data center SSDs drove the quarter. The company also set out a plan to return about 100 trillion won to shareholders for 2026.
Net income moved the other way. It fell 58% from the second quarter to 39.8 trillion won, the result of 32.6 trillion won in non-operating costs this quarter and a one-time Kioxia gain that had inflated the second quarter.
Key takeaways
- Revenue: 104.6155 trillion won, up 32% from Q2 and 328% from a year earlier.
- Operating profit: 83.3338 trillion won, up 38% quarter on quarter and 632% year on year. Operating margin was 80%, up from 76% in Q2 and 47% a year earlier.
- Net income: 39.7756 trillion won, down 58% from Q2's 93.9 trillion won, with a 38% net margin.
- Net cash reached 98.7 trillion won. Cash and equivalents rose 26.5 trillion won to 114.5 trillion won.
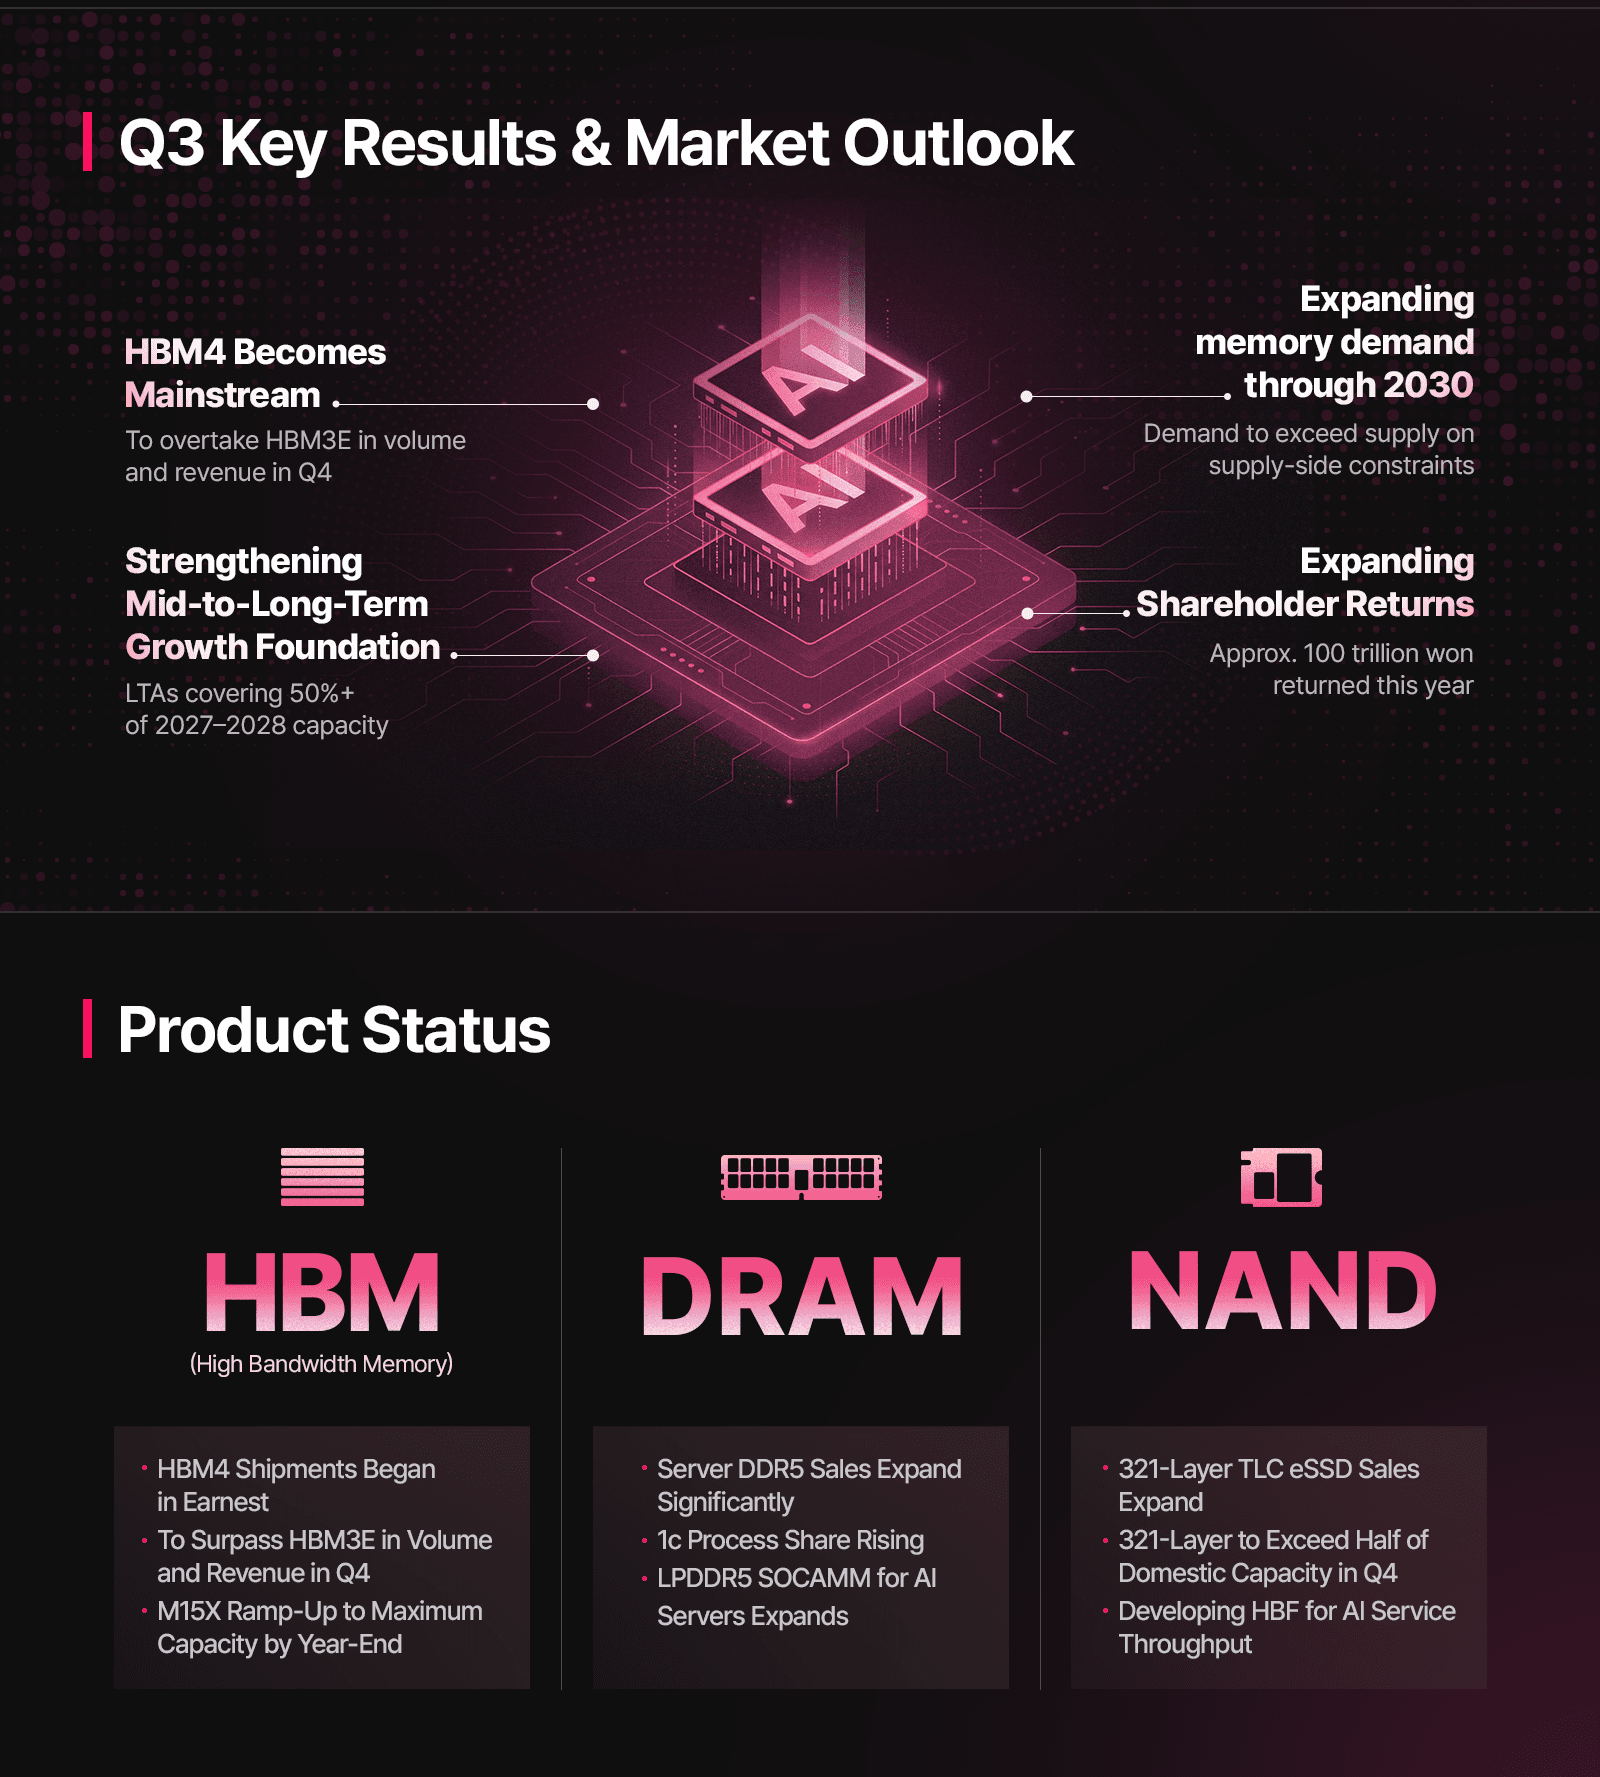
- SK hynix expects HBM4 to pass HBM3E in shipments and revenue from Q4 2026, and expects memory demand to exceed supply through 2030.
- Long-term agreements with 14 major customers cover more than half of 2027 and 2028 capacity.
- FY2026 shareholder returns of about 100 trillion won: at least 30 trillion won in dividends and at least 60 trillion won in buybacks and cancellations.
SK hynix Q3 2026 results in numbers
All figures are preliminary K-IFRS consolidated results. SK hynix notes they may change during the independent audit.
| 3Q26 | 2Q26 | QoQ | 3Q25 | YoY | |
|---|---|---|---|---|---|
| Revenue | 104.6155T won | 79.3187T won | +32% | 24.4489T won | +328% |
| Operating profit | 83.3338T won | 60.5426T won | +38% | 11.3834T won | +632% |
| Operating margin | 80% | 76% | +3 pts | 47% | +33 pts |
| Net income | 39.7756T won | 93.9226T won | -58% | 12.5975T won | +216% |
Source: SK hynix, 3Q26 financial results.
The balance sheet improved again. Borrowings fell 2.8 trillion won to 15.8 trillion won, so cash exceeds debt by 98.7 trillion won.
Operating profit came in well above forecasts. Reuters cited an LSEG SmartEstimate of 76.7 trillion won, so the result beat it by about 8.6%. Bloomberg's estimate was 77.5 trillion won. The shares closed nearly 11% higher at 1,487,000 won in Seoul on October 28, according to the same report.
What drove the quarter: HBM4, server DRAM and eSSD
HBM is stacked DRAM placed next to an AI accelerator, such as an NVIDIA GPU, to feed it data fast. It sells at a much higher price than ordinary DRAM, and SK hynix has been the largest supplier.
In DRAM, SK hynix says HBM4 shipments "began in earnest" in the third quarter and sales of server DDR5 rose sharply. In NAND, sales of eSSD (enterprise SSDs for data centers) built on its 321-layer TLC flash grew.
On the earnings call, CFO Kim Woo-hyun gave the price and volume split (TheElec call transcript):
| Shipments | Average selling price | |
|---|---|---|
| DRAM, 3Q26 | Up about 10% | Up in the high 20s %, quarter on quarter |
| NAND, 3Q26 | Down slightly | Up in the mid 20s % |
| DRAM, 4Q26 guidance | Up in the mid 20s % | Not given |
| NAND, 4Q26 guidance | Up in the mid single digits % | Not given |
Price did more of the work than volume. DRAM shipments grew about 10%, while average DRAM selling prices rose in the high 20s percent in a single quarter.
HBM demand is still larger than supply. The company said customer requests are more than twice the volume it can supply, and that it has finished negotiating 2027 HBM volumes and prices with its main customers. It did not say what share of DRAM revenue HBM now makes up, and it did not name customers. Reuters describes SK hynix as an NVIDIA supplier, and the AI infrastructure spending behind that demand shows up in results like Meta's Q3 2026 capex.
Why net income fell 58% while operating profit rose
The drop comes from items below operating profit. CFO Kim Woo-hyun said non-operating costs totaled 32.6 trillion won in the third quarter, including an 11.6 trillion won foreign-exchange loss as the exchange rate fell and a 22.9 trillion won valuation loss on investment assets (TheElec). The company did not say which investments the valuation loss came from.
The comparison quarter was also unusual. Second-quarter net income of 93.9 trillion won was far above that quarter's 60.5 trillion won operating profit. Korea JoongAng Daily reported that a large part of it was a one-time gain from selling Kioxia shares. Compared with a year earlier, third-quarter net income of 39.8 trillion won is still up 216%.
What SK hynix said about HBM4, supply and 2027
SK hynix's outlook rests on demand staying ahead of supply for years:
- HBM4 becomes the mainstream product from Q4 2026, passing HBM3E in both shipments and revenue.
- The M15X fab ramps to full capacity by year-end to add HBM4 output, and phase 1 of the Yongin cluster begins full-scale operation next year.
- The share of 1c DRAM, its sixth-generation 10nm-class process, rises quickly. Sales of DDR5 and LPDDR5-based SOCAMM modules for AI servers expand.
- 321-layer NAND will make up more than half of its domestic NAND capacity in Q4.
- The company expects demand to exceed supply through 2030, citing how hard leading-edge processes are and how long new fabs take to build.
Long-term agreements (LTAs) back that outlook. SK hynix has signed them with 14 major customers, including large cloud providers, and they cover more than 50% of its production capacity for 2027 and 2028. LTAs typically run five years, and prices move within an agreed range that reflects market conditions. SK hynix says investment will rise "significantly" in 2027 but did not give a capex figure.
The 100 trillion won shareholder return plan
For fiscal 2026, SK hynix plans to return about 100 trillion won:
- Cash dividends of at least 30 trillion won.
- Share buybacks and cancellations of at least 60 trillion won, including the 40 trillion won buyback announced in August. That buyback finished last week, and the shares will be cancelled shortly.
- A target of returning at least 50% of free cash flow.
For the third quarter, the board approved a 14 trillion won cash dividend, or 20,000 won per share: 10,000 won as a regular dividend and 10,000 won as a special dividend funded by gains on its Kioxia investment. It also approved a 20 trillion won buyback. Half of it, 10 trillion won, will be cancelled as a shareholder return. The other roughly 10 trillion won will go to employee compensation and is not counted in the return total.
CEO Kwak Noh-Jung said the company's principle "has been to share the majority of the gains from successful strategic investments with our shareholders." SK hynix also said it has dropped its review of an IPO for its NAND subsidiary Solidigm, which was meant to raise outside capital for Solidigm's facility expansion. Kwak said the decision reflected recent financial market volatility and the correction in semiconductor share prices.
How it compares
SK hynix now earns close to what the largest chipmakers earn, on less revenue:
| Company | Latest quarter | Revenue | Operating profit or margin |
|---|---|---|---|
| SK hynix | 3Q26 (to Sep 30) | 104.6T won | 83.3T won, 80% margin |
| Samsung Electronics | 3Q26 (to Sep 30) | 195.3T won | 107.4T won |
| Micron | FQ4 2026 (to Sep 3) | $54.23B | 80.7% GAAP operating margin |
Sources: SK hynix, Samsung Q3 2026 earnings call via Investing.com, Micron press release via Yahoo Finance.
By Seoul Economic Daily's tally, SK hynix's quarterly operating profit ranked third among global tech companies, behind Samsung and NVIDIA. The paper did not publish its exchange rate or say which fiscal quarters it compared, so treat the ranking as approximate.
Competition in HBM has tightened this year. Counterpoint Research's revenue-based figures, as reported by BigGo Finance, put SK hynix's HBM share at 50% in Q2 2026, down from 58% in Q1, while Samsung rose from 21% to 33%. Samsung said on its own call that HBM4 sales more than tripled from the previous quarter and that its 2027 HBM supply is sold out. For the China side of AI chips, see Cambricon's Q3 2026 results.
Risks to watch
- HBM4 timing. Citing Chosun Biz, TrendForce reported that HBM4 shipments "may have fallen short of expectations for a second consecutive quarter," pointing to delays in NVIDIA's Rubin rollout and longer chip tuning. SK hynix's own outlook is that HBM4 passes HBM3E in the fourth quarter.
- Memory prices. Most of the quarter's growth came from higher selling prices. Memory is a cyclical business, and the long-term agreements let prices move within an agreed range.
- Currency. The 11.6 trillion won foreign-exchange loss shows how much the won's level can move net income even when operations are strong.
- Competition. Samsung's rising HBM share and its sold-out 2027 HBM supply mean SK hynix is no longer the only large HBM4 supplier.
- Spending. Capex will rise significantly in 2027, but the company has not given a figure, so the effect on free cash flow, and on the 50% payout target, is not yet known.
FAQ
What were SK hynix's Q3 2026 earnings?
SK hynix reported revenue of 104.6 trillion won, operating profit of 83.3 trillion won and net income of 39.8 trillion won for the third quarter of 2026. Revenue rose 32% from the previous quarter and 328% from a year earlier, and the operating margin was 80%.
Why did SK hynix's net income drop in Q3 2026?
Net income fell 58% from the second quarter even though operating profit rose 38%. The company booked 32.6 trillion won in non-operating costs, including an 11.6 trillion won foreign-exchange loss and a 22.9 trillion won valuation loss on investment assets. The second quarter's net income had also been lifted by a one-time gain from selling Kioxia shares.
How much will SK hynix return to shareholders in 2026?
About 100 trillion won: at least 30 trillion won in cash dividends and at least 60 trillion won in share buybacks and cancellations. The Q3 dividend is 20,000 won per share, half of it a special dividend from Kioxia investment gains.
When does HBM4 become SK hynix's main HBM product?
SK hynix expects HBM4 to overtake HBM3E in both shipments and revenue from the fourth quarter of 2026, with the M15X fab at full capacity by year-end.
Sources
- SK hynix: SK hynix Announces 3Q26 Financial Results
- TheElec: SK hynix 3Q26 earnings call transcript (Korean)
- Reuters via Investing.com: SK Hynix Q3 profit jumps more than sevenfold
- Yahoo Finance: SK Hynix Q3 profit beats estimates
- Korea JoongAng Daily: SK hynix posts record Q2 profit
- Investing.com: Samsung Electronics Q3 2026 earnings call transcript
- Yahoo Finance: Micron reports record results
- Seoul Economic Daily: SK hynix Q3 operating profit ranks third among global tech
- BigGo Finance: Counterpoint HBM share data
- TrendForce: SK hynix 3Q earnings preview
This article is for informational purposes only and is not investment advice. Do your own research before making investment decisions.